True economic resilience isn’t about surviving a recession through frantic cost-cutting; it’s about building an ‘all-weather’ business that neutralises hidden vulnerabilities before the storm hits.
- Companies fail not from a lack of assets, but from a lack of liquid cash and an inability to adapt to sharp, unpredictable shocks.
- Proactive operational agility, such as reallocating resources and reskilling talent, consistently outperforms reactive, across-the-board budget slashes.
Recommendation: Shift your focus from simple cash flow management to a systematic ‘vulnerability mapping’ of your supply chain, customer base, and capital structure.
You remember the last downturn. The sleepless nights, the difficult decisions, the feeling of navigating a storm in a ship you suddenly realised was full of unseen leaks. You survived, but it felt more like luck than strategy. Now, as whispers of economic instability return, that anxiety is creeping back. The common advice starts to circulate: « cut costs, » « manage cash flow, » « focus on your core customers. » While not wrong, this advice is dangerously incomplete. It’s the equivalent of telling a sailor to « bail water » without teaching them how to read the weather charts or reinforce the hull.
This reactive, defensive posture is precisely what leaves so many businesses vulnerable, even those that appear strong on paper. The truth is, many UK businesses are sitting on a ‘burning platform’, as a CBI report warns, where deep interconnectedness with global markets creates vulnerabilities that aren’t visible on a standard balance sheet. The key to safeguarding your business isn’t found in simply doing less during a downturn, but in fundamentally rethinking the structure of your operations during periods of stability. But what if the real secret to invulnerability wasn’t about having more cash, but about understanding where your cash, supply lines, and revenue streams are most fragile?
This guide moves beyond the platitudes. We will dissect the hidden risks that bring down even profitable companies and provide a strategic framework for building genuine, proactive resilience. We’ll explore why cash-rich firms collapse, how to fortify your supply chain, why aggressive expansion can be a trap, and how to protect your operations from both national and localised shocks. It’s time to trade anxiety for strategy and build a business that is not just robust, but truly resilient.
To navigate this complex landscape, we’ve structured this analysis to address the most critical vulnerabilities one by one. The following sections provide a clear roadmap for auditing and reinforcing your business’s core operational pillars.
Summary: A Leader’s Guide to Economic Resilience
- Why Do Cash-Rich Companies Still Collapse During Sudden Market Shocks?
- How to Build Supply Chain Resilience Against Unpredictable Global Disruption?
- Reactive Cost Cutting vs Proactive Agility: Which Wins During Recessions?
- The Expansion Mistake That Bankrupts Firms During Periods of Volatility
- Hedging Currency Risks to Protect Profit Margins From Sterling Fluctuations
- Why Do Unpredictable Capital Flows Destroy UK SME Cash Reserves?
- Why Does Hyper-Focusing on One Region Guarantee Catastrophic Revenue Drops?
- How to Protect Your Enterprise From Devastating Localised Market Downturns?
Why Do Cash-Rich Companies Still Collapse During Sudden Market Shocks?
The most dangerous myth in business is that a healthy balance sheet is a guarantee of survival. We see companies with significant assets—property, equipment, intellectual property—suddenly become unable to make payroll during a sharp economic contraction. This is the ‘asset-rich, cash-poor’ phenomenon, a classic vulnerability that downturns mercilessly expose. The problem isn’t a lack of value, but a lack of liquidity. When credit markets tighten and customer payments slow, assets that seemed like a fortress become a prison, impossible to convert into spendable cash quickly enough to meet obligations.
This situation is escalating. In the UK, the pressure on businesses is becoming acute, with corporate insolvencies showing a worrying trend. In fact, recent data reveals that insolvencies are projected to end 2024 at 43% above the 2016-2019 average. This stark figure highlights that pre-pandemic stability metrics no longer apply. The trigger is often a sudden market shock that freezes a company’s working capital cycle. Revenue may be ‘on the books’ as accounts receivable, but if those clients are also struggling and delay payments, that revenue is useless for paying suppliers or staff this month. It’s a domino effect where a company’s theoretical wealth provides no protection against immediate cash-flow starvation.
True resilience, therefore, isn’t measured by the total value of your assets. It’s measured by your ‘cash conversion velocity’—the speed at which you can turn assets and receivables into usable funds—and the size of your unencumbered cash reserve. A business with £1 million in machinery and £10,00t in the bank is far more vulnerable than one with £500,00t in machinery and £150,00t in easily accessible funds. The first step in safeguarding your operations is to conduct a brutal, honest audit of your liquidity, separating real, spendable cash from illiquid ‘paper’ wealth.
How to Build Supply Chain Resilience Against Unpredictable Global Disruption?
For decades, the mantra for supply chains was « efficiency. » Just-in-time delivery and single-sourcing from low-cost regions were seen as strategic advantages. Today, those same strategies are a primary source of vulnerability. A single factory lockdown, a blocked shipping canal, or a new trade tariff can bring a UK business to a halt. The recent past has shown that these are not black swan events; they are the new normal. Indeed, a TMX Global study found that supply chain disruptions are costing the UK over £12 billion annually. This isn’t a cost of doing business; it’s a tax on a lack of resilience.
Building resilience requires a fundamental shift from optimising for cost to optimising for continuity. This begins with deep-tier supply chain mapping. Most businesses know their ‘Tier 1’ suppliers—the companies they pay directly. But very few know their ‘Tier 2’ (their supplier’s supplier) or ‘Tier 3’ suppliers. It is often in these hidden depths that the greatest risks lie—a single component manufacturer in a politically unstable region, for example, that supplies your entire industry.
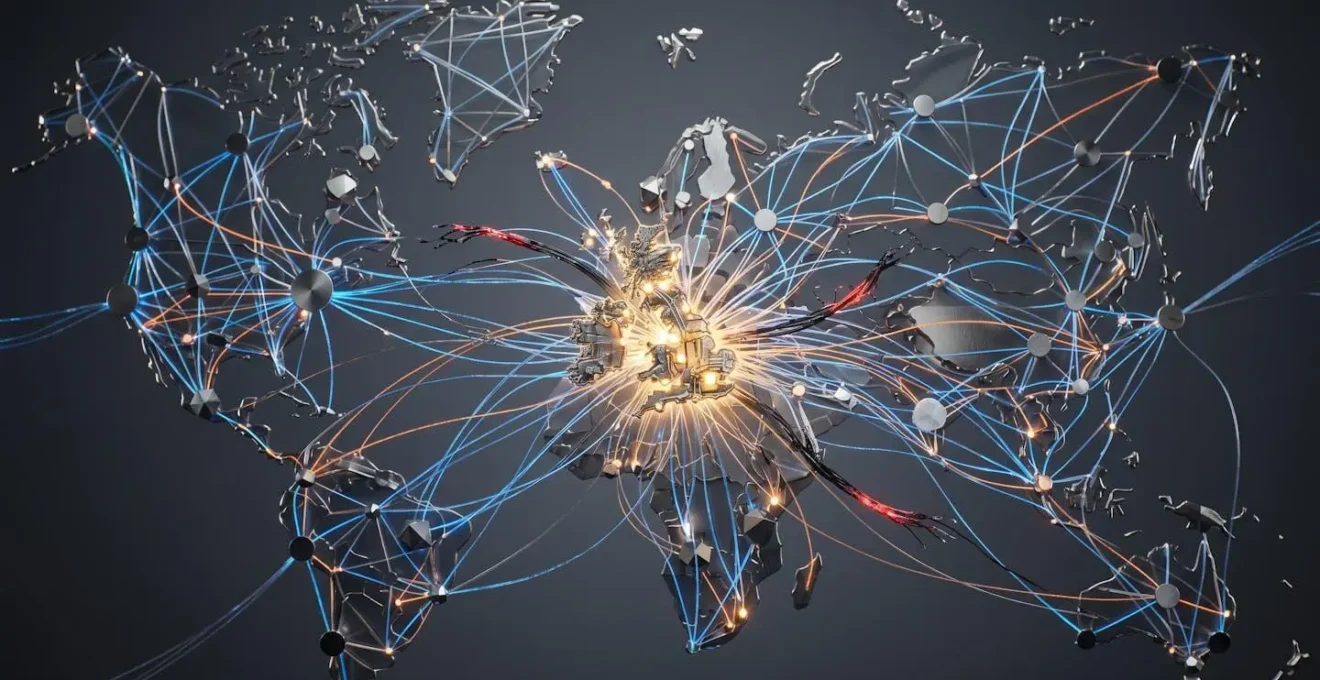
As the visualisation above suggests, modern supply chains are intricate, global networks. A single point of failure can have cascading effects. The goal is to move from a fragile, linear chain to a robust network of options. This involves several key actions:
- Supplier Diversification: Identify and qualify alternative suppliers, even if they are slightly more expensive. The premium you pay is an insurance policy against catastrophic failure. Prioritise a mix of local and international suppliers to balance cost with security.
- Geographic Diversification: Avoid concentrating your supply base in a single country or region. A ‘China +1’ strategy is a start, but a multi-region approach is better.
- Strategic Buffers: While just-in-time is efficient, ‘just-in-case’ is resilient. Hold strategic inventory of critical components, especially those with long lead times or few suppliers. Leveraging UK Freeports like Teesside or Solent can be a capital-efficient way to do this.
- Collaborative Transparency: Work with your Tier 1 suppliers to gain visibility into their own supply chains. Shared risk is mitigated risk.
Reactive Cost Cutting vs Proactive Agility: Which Wins During Recessions?
When the first signs of a downturn appear, the knee-jerk reaction in many boardrooms is to mandate across-the-board cost cuts. « Everyone trim their budget by 20%. » While this feels decisive, it’s often a catastrophic mistake. This approach treats all expenses as equal, punishing efficient departments along with inefficient ones and slashing investments that are critical for recovery. It’s the equivalent of a starving person eating their seed corn. Research from Korn Ferry confirms the alternative path, stating, « Organizations with high agility and resilience are significantly better equipped to navigate complex shocks. »
Proactive agility is the superior strategy. It doesn’t mean spending more; it means spending smarter. Instead of indiscriminate cuts, an agile organisation reallocates resources with surgical precision. It asks, « Where can we invest now to gain market share when our competitors are retreating? » and « Which internal processes can we streamline to free up capital for strategic initiatives? » This requires a deep understanding of the business and the courage to invest when others are panicking.
The difference in outcomes between these two approaches is not subtle. It determines whether a company emerges from a recession weakened and behind the curve, or stronger and with a greater market share. The table below illustrates the stark contrast in thinking.
| Approach | Reactive Cost-Cutting | Proactive Agility | Outcome |
|---|---|---|---|
| Marketing Investment | Slash budgets across the board | Reallocate to high-ROI channels | Market share gain/loss |
| R&D Spending | Freeze all innovation projects | Focus on rapid prototyping | Competitive position in recovery |
| Talent Management | Widespread redundancies | Reskilling & redeployment | Organizational capability |
| Operational Efficiency | Arbitrary 20% cuts | Lean process optimization | Sustainable cost structure |
As this analysis of volatile-era strategies shows, every function of the business presents a choice: panic and retreat, or analyse and advance. Slashing the marketing budget cedes ground to rivals. Freezing R&D ensures you’ll have no new products when the economy recovers. Widespread redundancies destroy institutional knowledge and morale. Proactive agility, by contrast, views the downturn as an opportunity to sharpen the organisation, redeploy talented people to new challenges, and double down on what works, positioning the company for dominant growth during the inevitable recovery.
The Expansion Mistake That Bankrupts Firms During Periods of Volatility
Periods of economic boom, often fueled by low interest rates or stimulus spending, can sow the seeds of future failure. A common and devastating error is mistaking a temporary, sector-wide surge for a permanent shift in baseline demand. This leads to debt-fueled overexpansion. Businesses take on significant loans to increase capacity—new facilities, more staff, larger inventory—only to find themselves with a crippling cost structure when the market inevitably reverts to the mean.
We saw a clear example of this in the UK’s post-COVID economy. SMEs in sectors like ‘staycation’ leisure and home improvement experienced unprecedented demand. Many expanded aggressively, only to face a severe contraction as consumer spending patterns normalised and disposable incomes were squeezed by inflation. The debt taken on during the boom, often at what seemed like attractive low rates, became an anchor that drowned them when revenues fell. This is a classic case of what happens when strategic planning is driven by optimistic revenue forecasts rather than a sober assessment of profit resilience.
This disconnect between optimism and reality is a persistent psychological trap for entrepreneurs. A Vistage survey perfectly captures this sentiment, revealing that while 56% of SMEs expect revenue growth, only 38% expect profit growth. This gap is where danger lies. It suggests many businesses are chasing top-line growth at the expense of bottom-line health, a strategy that is unsustainable during periods of economic volatility. Chasing revenue often means taking on less profitable clients, offering discounts, or entering new markets without fully understanding the costs, all of which erodes the very profit margin needed to build cash reserves.
The antidote to this is disciplined, profit-focused growth. Before any expansion, the critical question is not « Can we get more sales? » but « Will this expansion generate sustainable, high-quality profit that strengthens our balance sheet? » This requires war-gaming a recession scenario: what would our debt service look like if revenues dropped by 30%? Can we scale back these new operations without incurring massive write-downs? If the answers are unsettling, the expansion plan is a vulnerability, not an opportunity.
Hedging Currency Risks to Protect Profit Margins From Sterling Fluctuations
For any UK business that imports materials, exports goods, or has international clients, the value of the Pound Sterling is not an abstract economic indicator; it’s a direct and volatile component of your profit margin. A sudden 5% drop in GBP can wipe out the entire profit on a major deal. In an era of geopolitical instability and economic uncertainty, assuming currency stability is a high-risk gamble. Failing to manage this exposure is one of the most common and easily avoidable vulnerabilities for UK SMEs.
Many business owners are hesitant to engage with currency hedging, viewing it as complex, expensive, or something reserved for large corporations. This is a misconception. Modern financial tools have made currency risk management accessible to businesses of all sizes. The cost of not hedging is almost always higher than the cost of a disciplined hedging strategy. It’s about turning an unpredictable variable into a predictable cost, allowing for accurate pricing and forecasting. This is a core component of building financial shock absorbers into your business model.
Implementing a basic currency risk management framework doesn’t have to be overly complicated. It begins with identifying your net exposure and setting clear policies. A solid starting point for any SME includes:
- Evaluating Hedging Tools: Understand the difference between forward contracts (which lock in a future exchange rate) and currency options (which give you the right, but not the obligation, to exchange at a certain rate). Forward contracts offer certainty but no upside if the rate moves in your favour, while options offer flexibility at a premium.
- Implementing Cash Flow Hedging: For predictable, recurring international transactions (like paying a key overseas supplier each month), use forward contracts to lock in costs and protect your margins.
- Dynamic Pricing: For international sales, consider pricing mechanisms that adjust based on significant currency movements or price goods in the client’s local currency and hedge the exposure back to GBP.
- Policy and Review: Establish a formal hedging policy that outlines your risk tolerance and objectives. This policy should be reviewed quarterly to ensure it remains aligned with market conditions and your business’s evolving needs.
Why Do Unpredictable Capital Flows Destroy UK SME Cash Reserves?
Cash reserves are the lifeblood of a business, but they can be surprisingly fragile. One of the most insidious threats comes from unpredictable capital flows, particularly those linked to external funding and government support schemes. While intended to help, these capital injections can create a dangerous dependency, masking underlying business model flaws and leading to a crisis when the support is withdrawn or repayment obligations begin.
Research on UK SMEs during the COVID-19 pandemic provided a stark lesson in this regard. While grant funding offered immediate and vital relief, businesses that became overly reliant on programmes like the Recovery Loan Scheme found themselves in a precarious position. The loans enabled them to survive, but not necessarily to adapt. They postponed the difficult work of fixing inefficient processes or pivoting away from failing products. When the time came to start repaying these loans, the fundamental weaknesses remained, but now with an added layer of debt service that their fragile cash flow could not support.
This dynamic is exacerbated by the desperation for funding that a volatile economy creates. A notable surge in a recent survey shows 70% of SMEs are seeking funding in 2025, a dramatic increase from 30% in 2024. When businesses are in survival mode, they are more likely to accept funding from any available source without rigorously stress-testing their ability to repay it under adverse conditions. This creates a cycle of vulnerability: an initial shock drives a need for external capital, which in turn creates a new, fixed cost (debt repayment) that makes the business even more susceptible to the *next* shock. It’s a financial trap that can destroy even a fundamentally sound business.
Building resilience against this requires a disciplined approach to capital. External funding should be used for strategic investment in efficiency or growth, not to cover up operational shortfalls. Every new loan or investment should be modelled against a « recession-case » scenario. A business that can’t service its debt with a 30% drop in revenue is a business that is taking on too much risk. The goal is to use capital to build a stronger foundation, not to patch over a crumbling one.
Why Does Hyper-Focusing on One Region Guarantee Catastrophic Revenue Drops?
While global supply chains present one form of risk, an equally significant threat can be found much closer to home: regional economic concentration. Many UK SMEs build their success by serving a dominant local industry or a specific geographic market. They become experts in their niche, their fortunes intertwined with the health of their region. This can be a powerful driver of growth during good times, but it creates extreme vulnerability when that specific region or industry faces a downturn. It’s a classic case of putting all your eggs in one geographic basket.
The UK provides many examples of this phenomenon. Businesses in the Midlands that are heavily reliant on the automotive sector, or companies in Aberdeen that primarily serve the oil and gas industry, face existential threats when those core sectors struggle. This isn’t theoretical; a study on crisis impacts found that medium-sized enterprises in such concentrated areas showed 60.8% negative impact rates during recent crises. When the primary local employer announces layoffs or a major project is cancelled, the ripple effect on consumer spending and business-to-business services is immediate and devastating for companies with no revenue streams outside that bubble.
As researchers Brown et al. noted in a study on crisis impacts, « Due to the critical significance of small businesses to the UK economy, they serve as an excellent ‘unit of analysis’ and a strong indicator for assessing regional resilience. » Your business’s resilience is inextricably linked to the resilience of your region. If your customer base is 100% located within a 50-mile radius and is dominated by a single industry, your risk profile is dangerously high, regardless of how well you manage your internal operations. A local flood, a factory closure, or a change in local government policy can have a more significant impact on your business than a national recession.
Safeguarding against this requires a deliberate strategy of geographic revenue diversification. This doesn’t mean abandoning your home market, but systematically building a presence and customer base in other, uncorrelated UK regions. The goal is to ensure that a downturn in one area is buffered by stable or growing revenues in another. This transforms your business from a regional player subject to local whims into a national entity with a more balanced and resilient revenue profile.
Key takeaways
- True wealth in a crisis is liquidity; being ‘asset-rich, cash-poor’ is a state of extreme vulnerability when markets freeze.
- Proactive agility—reallocating resources and reskilling talent—consistently outperforms reactive, across-the-board cost-cutting, positioning a company to win during the recovery.
- Resilience is built by systematically mapping and mitigating hidden dependencies, whether in your multi-tiered supply chain or your concentrated regional customer base.
How to Protect Your Enterprise From Devastating Localised Market Downturns?
Acknowledging the risk of regional concentration is the first step; actively mitigating it is what builds a resilient enterprise. Protecting your business from a localised downturn requires a proactive and data-driven strategy to diversify your revenue streams geographically. The goal is to build a balanced portfolio of regional markets so that a slump in one area doesn’t cripple the entire organisation. This isn’t about guesswork; it’s about using publicly available data to make informed strategic decisions.
The Office for National Statistics (ONS) provides a wealth of data that can be used to create an early warning system and identify opportunities. By monitoring regional data on unemployment, Gross Value Added (GVA), and business confidence, you can spot signs of economic decline in one region and, conversely, identify areas of robust economic health ripe for expansion. This intelligence-led approach allows you to deploy resources—like targeted digital advertising or a small sales presence—to test and build a foothold in more resilient UK regions before a crisis hits your home turf.
Furthermore, a localised downturn can present strategic opportunities for the well-prepared. As weaker, over-leveraged competitors in other regions begin to struggle, it can create opportunities for strategic acquisition at a favourable price. This allows you to acquire customers, talent, and market share that would have been far more expensive in a booming economy. Resilience is not just about defence; it’s about being strong enough to play offence when others are forced to retreat. One of the biggest threats during any downturn is the cascading effect of bad debt, and evidence from Sage indicates UK small businesses were owed an estimated £112 billion in unpaid invoices by the end of 2024, a stark reminder of how interconnected regional risks are.
Your Regional Resilience Audit Checklist
- Points of contact: List all revenue streams and map the geographic location of your top 80% of customers. Is there a concentration in one post code, city, or region?
- Collecte: Inventory your current marketing and sales efforts. What percentage of your budget is spent targeting your home region versus other UK regions?
- Cohérence: Confront your customer concentration map with ONS regional economic health data. Are your key markets showing signs of economic stress (rising unemployment, falling GVA)?
- Mémorabilité/émotion: Identify two UK regions with strong economic indicators that are uncorrelated with your primary market. What are the unique needs or pain points of customers in those regions?
- Plan d’intégration: Develop a low-cost pilot project to test one of these new regions. This could be a geographically-targeted digital ad campaign or a partnership with a local distributor. Set clear metrics for success.
Now that you understand the framework of vulnerabilities—from liquidity traps and supply chains to regional concentration—the next step is to apply it. A passive understanding is not enough. Begin your business’s resilience audit today to actively safeguard its future and transform anxiety into a clear, actionable strategy.