The single biggest mistake in corporate portfolio management is using one set of rules to govern vastly different types of assets, inevitably strangling innovation or starving cash cows.
- Success depends on creating parallel governance systems, each tailored to a specific « investment horizon »—core business, emerging ventures, and disruptive bets.
- Applying a one-size-fits-all approach to metrics, funding, and reviews guarantees underperformance and drains capital.
Recommendation: Shift from a monolithic management style to a dynamic, multi-track framework that actively balances stability and growth to secure long-term ROI.
As a Chief Strategy Officer, you operate at the nexus of competing demands. The board wants predictable, quarterly returns from your established business units. Simultaneously, they expect you to pioneer the next wave of disruptive growth. The conventional advice is a frustrating paradox: « cut costs » and « be more innovative. » This often leads to a reactive cycle of starving promising ventures of oxygen or, conversely, allowing sentimental « pet projects » to drain resources that should be fortifying your core revenue streams. The struggle to balance the demands of the present with the needs of the future is a constant source of strategic tension.
Many leaders believe the answer lies in better financial forecasting or more aggressive diversification. They chase shiny objects or double down on what’s always worked, hoping for a different outcome. But what if the fundamental problem isn’t the assets themselves, but the singular, rigid system used to manage them all? The truth is, you cannot evaluate a nascent, high-risk technology with the same P&L metrics you apply to a market-leading cash cow. Trying to do so is like trying to use the same training regimen for a marathon runner and a sprinter—you end up with two exhausted, underperforming athletes.
The key to unlocking sustainable, long-term ROI is not to find a « perfect » balance, but to build a strategic framework that allows multiple, distinct management models to operate in parallel. This article moves beyond the platitudes of « risk vs. reward » to provide a concrete, defensible methodology for the modern CSO. We will explore how to structure your portfolio across different « horizons » of growth, each with its own governance, metrics, and management cadence. This approach provides the clarity needed to protect your core business, nurture emerging opportunities, and make bold, calculated bets on the future, transforming portfolio management from a game of chance into a discipline of strategic execution.
This guide provides a structured approach to rethinking your entire portfolio strategy. Below, we’ll delve into the specific frameworks, decisions, and actions required to build a resilient and high-growth corporate portfolio.
Summary: A CSO’s Guide to Mastering Strategic Portfolio Management
- Why Focusing Exclusively on Immediate Costs Ruins Your Strategic Portfolio?
- How to Balance High-Risk Innovations With Steady Revenue-Generating Projects?
- Consolidating Assets vs Diversification: Which Secures Better Capital Growth?
- The Pet Project Attachment That Diverts Funds From Winning Investments
- Divesting Underperforming Assets to Free Up Vital Investment Capital
- How to Diversify Corporate Funds Across Low-Risk Sectors Successfully?
- Organic Market Expansion vs Aggressive Acquisitions: Where Should Capital Go?
- How to Build Strategic Investment Portfolios That Protect Corporate Cash Reserves?
Why Focusing Exclusively on Immediate Costs Ruins Your Strategic Portfolio?
The relentless pressure for short-term profitability often forces leaders into a defensive crouch, where every decision is viewed through the narrow lens of immediate cost reduction. This mindset, while essential for operational efficiency, is devastating when applied to strategic portfolio management. It systematically undervalues future growth and creates an organizational immune response to any initiative that doesn’t promise a quick return. The result is a slow, self-inflicted slide into irrelevance, as the core business becomes brittle and the pipeline of future opportunities runs dry.
To break this cycle, a more sophisticated framework is needed. The McKinsey Three Horizons model provides a powerful lens for this task. It reframes the portfolio not as a monolithic entity, but as three distinct categories:
- Horizon 1 (H1): The core businesses that provide today’s cash flow. The focus here is on efficiency, optimisation, and defending market share.
- Horizon 2 (H2): Emerging opportunities with proven potential, such as expanding into adjacent markets or scaling a new product line. The focus is on growth and entrepreneurship.
- Horizon 3 (H3): Nascent ideas and technologies that could be future game-changers. This is the realm of R&D and pilot projects, where the focus is on learning and discovery.
This model reveals that an exclusive focus on cost-cutting is essentially an over-investment in H1 at the expense of H2 and H3. Research validates this perspective, showing that companies that strategically allocate resources across all three horizons can achieve a 30% greater return on investment compared to those who don’t. It’s not about abandoning cost control; it’s about applying it to the right horizon while protecting the investments that will fuel tomorrow’s profits.
Ultimately, shifting the conversation from « how much does this cost? » to « in which horizon does this investment fit? » is the first step toward building a truly strategic and resilient portfolio.
How to Balance High-Risk Innovations With Steady Revenue-Generating Projects?
The core tension in portfolio management lies in reconciling the predictable, steady nature of established assets with the volatile, uncertain world of innovation. Traditional management systems excel at overseeing the former but are notoriously poor at nurturing the latter. Applying the same rigid ROI calculations and annual budget cycles to a Horizon 3 « moonshot » project as you would to a Horizon 1 cash cow is a recipe for failure. The innovative project will invariably be judged as too risky, too slow, or too unprofitable and will be starved of resources before it has a chance to prove its potential.
The solution is not to find a single, magical balance point, but to create separate « governance tracks » for different risk profiles. Each horizon requires a distinct approach to management, measurement, and funding. A stable H1 asset may be reviewed quarterly against strict P&L targets. An emerging H2 venture might need monthly reviews focused on market adoption and scaling metrics. A high-risk H3 initiative could require weekly check-ins focused on learning milestones and validating key assumptions, with funding released in stages based on progress.
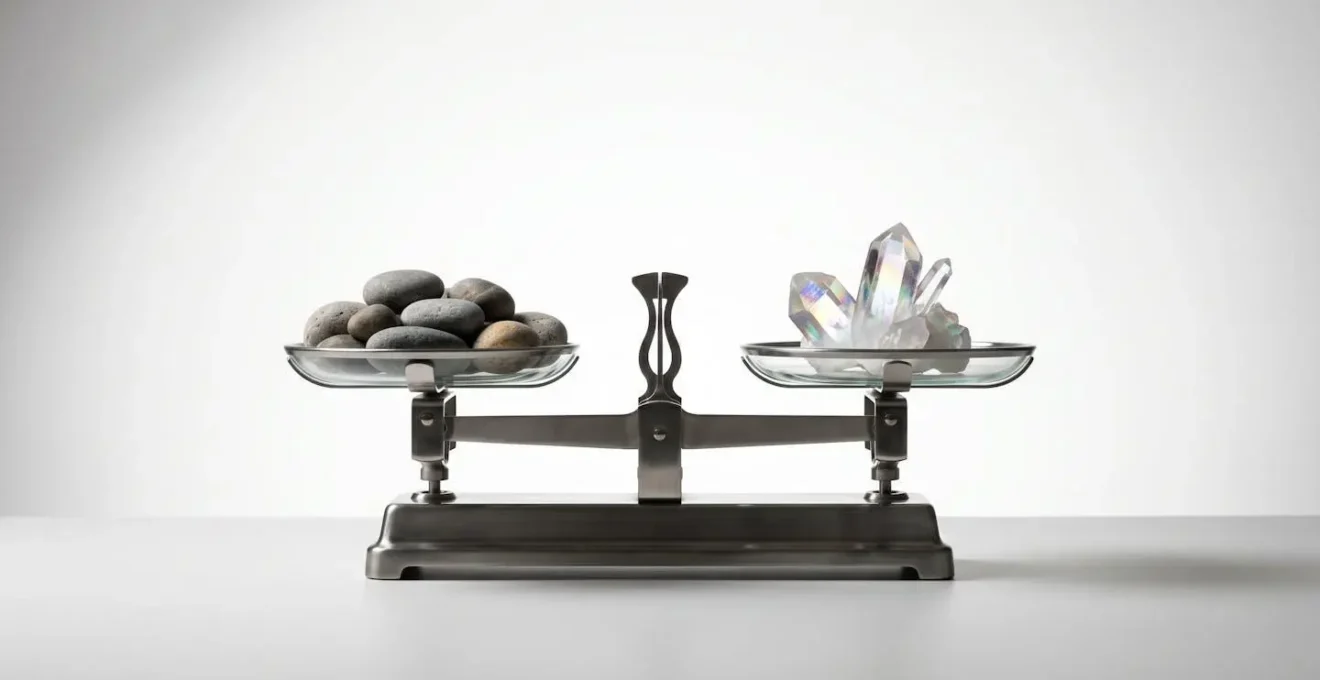
This visual metaphor of the scale perfectly captures the challenge. You are not balancing identical weights; you are balancing dense, stable stones (H1) with lightweight but potentially brilliant crystals (H3). They require different handling. The table below illustrates how different portfolio management approaches align with varying levels of risk and time horizons, reinforcing the need for a tailored strategy.
| Approach | Risk Level | Management Style | Expected Returns | Time Horizon |
|---|---|---|---|---|
| Active Portfolio | High | Frequent trading, market timing | Above market | Short-term |
| Passive Portfolio | Low-Medium | Index tracking, buy-and-hold | Market average | Long-term |
| Strategic Allocation | Medium | Regular rebalancing | Risk-adjusted | Long-term |
| Tactical Allocation | High | Dynamic adjustments | Opportunistic | Short to medium |
By creating these parallel systems, you allow each part of your portfolio to be judged by the metrics that matter for its specific stage of development, effectively balancing risk and reward across the entire enterprise.
Consolidating Assets vs Diversification: Which Secures Better Capital Growth?
The strategic debate between consolidating capital into proven winners and diversifying across new opportunities is often framed as a binary choice. However, viewed through the Three Horizons framework, it becomes a more nuanced allocation puzzle. The answer is not « either/or » but « both, in the right proportions. » The question isn’t whether to consolidate or diversify, but *where* to do each.
For your Horizon 1 assets—the core of your business—consolidation is key. This is where you double down on what works, reinvesting capital to build efficiencies, defend market share, and extract maximum value. The temptation to spread H1 profits thinly across a dozen speculative ventures must be resisted. The data often supports this focused approach; for instance, over the last decade, US stock markets have beaten developed ex-US and emerging markets 75% of the time, suggesting that concentrating capital in a high-performing « market » can be a powerful strategy. Applying this logic internally means reinforcing your strongest divisions.
Conversely, diversification is the primary strategy for Horizon 3. This is where you are planting seeds for the future. You don’t know which seed will grow into a mighty tree, so you plant several in different plots. H3 diversification is not about financial engineering but about exploring a variety of technological, market, and business model possibilities. The goal isn’t immediate ROI on any single bet, but the collective knowledge gained and the increased probability that one of these bets will evolve into a future H2 or H1 business. As a McKinsey survey noted, the speed and quality of these strategic decisions are paramount. The ability to quickly decide whether to nurture, pivot, or cut a diversified H3 experiment is a critical capability.
This balanced approach ensures that your core business remains robust and well-funded, while also providing the fertile ground necessary for future growth engines to emerge.
The Pet Project Attachment That Diverts Funds From Winning Investments
One of the most insidious threats to a strategic portfolio is the « pet project »—an initiative that continues to receive funding and attention not because of its strategic merit or performance, but due to emotional attachment, internal politics, or sunk-cost fallacy. These projects act as black holes, diverting capital, talent, and leadership focus away from more deserving investments and distorting the entire portfolio. They are often championed by influential executives and exist outside of objective scrutiny, making them notoriously difficult to dismantle.
The only effective antidote to this bias is a system of radical transparency and objective evaluation. This is where a formal strategic portfolio management framework becomes a CSO’s greatest ally. By forcing every project, regardless of its origin or champion, to be scored against the same clear, pre-defined strategic criteria, the framework exposes those that fail to deliver value. A professional services firm, for example, used the Three Horizons framework to redesign its growth strategy. The structured approach not only enabled them to achieve a 12% growth in Horizon 1 revenue but also led to a 20% increase in viable Horizon 3 initiatives by reallocating resources away from underperforming projects.
Implementing such a system requires discipline and a commitment to data over opinion. It involves creating transparent scoring models, establishing regular portfolio review cadences where termination is a normal and expected outcome, and documenting clear exit criteria before a project even begins. This depersonalizes the decision-making process, shifting the conversation from « Are we killing Bob’s project? » to « Does this project still meet the objective criteria to deserve funding? »
Action Plan: How to Eliminate Portfolio Bias
- Implement objective project prioritization: Use evaluation data to expose ‘pet projects’ that don’t deliver value against strategic goals.
- Create transparent scoring systems: Develop and communicate clear criteria that bring objectivity to the selection and review process.
- Establish regular portfolio review cadences: Normalize the process of reviewing and, if necessary, terminating projects to make it a routine business decision.
- Utilize the Efficient Frontier concept: Map projects based on value vs. cost/risk to visually identify which initiatives deliver the most strategic return and deserve funding.
- Document and communicate clear exit criteria: Define the conditions for project termination or pivoting before the project is initiated to remove ambiguity later.
By substituting subjective attachment with objective analysis, a CSO can ensure that capital flows to the investments with the highest potential for long-term ROI, not just the ones with the loudest champions.
Divesting Underperforming Assets to Free Up Vital Investment Capital
Just as a gardener must prune dead branches to encourage new growth, a strategist must actively divest underperforming assets to free up capital for more promising ventures. Divestment is not an admission of failure; it is a critical, proactive component of dynamic portfolio management. Yet, many organizations hesitate, burdened by inertia, sentimentality, or the fear of booking a loss. This hesitation is costly, as it keeps valuable resources—capital, talent, and management attention—trapped in a low-return or negative-return part of the portfolio.
A strategic approach to divestment requires a clear-eyed, unsentimental assessment of every asset against two key questions: 1) Does this asset still align with our long-term strategy? and 2) Is it the best possible owner for this asset? Sometimes a business unit may be profitable but no longer fits the company’s strategic direction. In such cases, selling it to a new owner for whom it is a core asset can create value for both parties. This proactive mindset is reflected in wider market trends, where active management is gaining traction; for instance, in the investment world, the US market saw growth of 468 new active ETFs in 2024, signaling a shift towards more dynamic portfolio decisions.
The act of divestment should be seen as a strategic « pruning, » as visualized above. It is a precise action designed to strengthen the overall health and vitality of the corporate portfolio. The capital and resources freed from a divested H1 asset can be redeployed to accelerate a promising H2 venture or to fund a portfolio of H3 experiments. This transforms divestment from a painful write-off into a powerful mechanism for capital reallocation, fueling the cycle of renewal that is essential for long-term growth.
Therefore, a regular, disciplined divestment review process is not just good financial hygiene; it is a fundamental driver of corporate strategy and a cornerstone of maximising long-term ROI.
How to Diversify Corporate Funds Across Low-Risk Sectors Successfully?
Diversifying into low-risk sectors is a classic strategy to protect corporate cash reserves and stabilize overall portfolio returns. However, « successful » diversification is far more nuanced than simply spreading capital across different industries. A common mistake is treating it as a box-ticking exercise, leading to a collection of disconnected, mediocre assets that add complexity without adding significant strategic value. True success lies in applying the same strategic rigor to low-risk investments as you would to high-growth ventures.
Firstly, diversification should be strategic, not random. The goal is to identify sectors that are not only low-risk but also have low correlation with your core business. This provides a genuine hedge against downturns in your primary markets. Secondly, investor sentiment and market dynamics matter. For example, recent investor allocation data shows 18.4% of portfolios included commodities in 2024, down from 22% in 2023. This doesn’t mean commodities are a bad investment, but it indicates a shift in the market’s perception of risk and return, a factor that a prudent strategist must consider.
The most effective approach is to think of this diversification as building a portfolio of external Horizon 1 assets. You are looking for stable, predictable cash-flow-generating businesses that require minimal management intervention from your core team. These could be investments in real estate, infrastructure funds, or dividend-paying equities in non-cyclical industries. The key is to focus on initiatives with the greatest potential to deliver steady, reliable value with the least amount of distraction from your primary strategic goals. Organizations that implement holistic portfolio management report improved ROI precisely because it allows them to focus resources effectively, even within their « safer » investment buckets.
Ultimately, successful low-risk diversification isn’t about collecting assets; it’s about building a resilient, counter-cyclical buffer that protects the mothership and ensures you have the stability to continue funding your higher-risk, higher-growth initiatives in H2 and H3.
Organic Market Expansion vs Aggressive Acquisitions: Where Should Capital Go?
The choice between growing organically and acquiring growth is a perennial strategic dilemma. Each path has distinct implications for speed, risk, and resource requirements. Placing this decision within the Three Horizons framework provides critical clarity. The optimal path is not universal but is highly dependent on which horizon you are targeting for growth.
Organic growth is typically the preferred vehicle for Horizon 1. It involves leveraging your existing capabilities, brand, and customer relationships to incrementally expand your market share or enhance your products. While slower, it is generally lower-risk and less capital-intensive upfront. It strengthens your core and is managed through established internal processes. Conversely, aggressive acquisitions are often a powerful tool for entering Horizon 2. An acquisition can provide immediate access to a new market, new technology, or a new customer segment, allowing you to build a significant position much faster than you could organically. However, it comes with a higher price tag and the substantial risks of integration complexity and culture clash.
As McKinsey & Company emphasizes in their thinking around the Three Horizons model, successful companies must be capable of « developing several businesses in parallel without regard to their stage of maturity. » This underscores the need for a multi-modal approach. Your organization must be adept at both the disciplined execution of organic H1 growth and the more dynamic, high-stakes process of strategic H2 acquisitions. The table below outlines the trade-offs in a clear format.
| Strategy | Speed to Market | Resource Requirements | Risk Level | Integration Complexity |
|---|---|---|---|---|
| Organic Growth | Slow | Internal capabilities | Low-Medium | Minimal |
| Strategic Acquisition | Fast | High capital | High | Complex |
| Joint Ventures | Medium | Shared resources | Medium | Moderate |
| Licensing | Fast | Low capital | Low | Simple |
Therefore, capital allocation shouldn’t be dogmatically tied to one growth strategy. It should be deployed dynamically, using acquisitions to jumpstart H2 ambitions while relying on organic growth to fortify the H1 foundation.
Key takeaways
- Strategic failure often stems from applying a single management model to the entire portfolio; success requires parallel governance tracks for core (H1), emerging (H2), and future (H3) assets.
- Overcoming bias and « pet projects » is impossible without a transparent, objective evaluation framework that forces all initiatives to justify their claim on corporate resources.
- Divestment is not failure; it is a strategic tool for capital reallocation, pruning underperforming assets to free up resources for high-potential growth ventures.
How to Build Strategic Investment Portfolios That Protect Corporate Cash Reserves?
Building a portfolio that both drives aggressive growth and protects existing cash reserves may seem contradictory, but it is the ultimate objective of strategic portfolio management. The key is to view the portfolio not as a single entity, but as a balanced ecosystem where different parts play different roles. The stability and cash flow from your robust Horizon 1 assets provide the « reserves » and the financial foundation that allows you to take calculated risks in Horizons 2 and 3.
Protecting cash reserves, therefore, is not about avoiding risk altogether. It’s about consciously managing and containing it. This is achieved by implementing the disciplined, multi-track governance system we’ve discussed. You protect the corporation by ensuring that the bulk of your capital and resources remains in proven H1 businesses, while allocating a smaller, strictly controlled portion of capital to higher-risk H2 and H3 ventures. A common heuristic is the 70-20-10 rule: 70% of investment in H1, 20% in H2, and 10% in H3. This is not a rigid law but a starting point for strategic discussion.
Furthermore, each investment must be tied to clear strategic objectives and KPIs. This ensures accountability and allows for real-time monitoring and adjustment. For an H2 marketing initiative, for example, a target ROI might be set; for context, studies show that on average, B2B marketing achieved a 5:1 average ROI ratio. For an H3 project, the KPI might not be financial at all, but a learning goal like « validate customer demand for X feature. » By maintaining disciplined review cycles and adjusting investment flows based on strategic relevance and performance against these KPIs, you create a dynamic, self-correcting system. This ensures that cash reserves are not just passively protected, but are actively fueling a balanced engine of sustainable, long-term growth.
To put these strategies into practice, the next logical step is to conduct a full audit of your current portfolio, classifying every asset and project into the Three Horizons and evaluating them against a newly established, objective set of strategic criteria.