Successful expansion into emerging markets is not about avoiding risk, but about systematically engineering control. For UK business owners, this means abandoning familiar domestic models and instead building robust legal, financial, and compliance structures. This guide provides a consultant’s framework for de-risking high-growth opportunities by focusing on structural arbitrage, compliance firewalls, and sophisticated hedging, turning volatility into a manageable—and profitable—variable.
For a UK business owner, the phrase « emerging markets » conjures a potent mix of opportunity and terror. The prospect of tapping into the explosive growth of Southeast Asia or Latin America is tantalising, yet the path is fraught with horror stories of regulatory nightmares, currency collapses, and intellectual property theft. The standard advice— »do your due diligence » or « understand the culture »—feels woefully inadequate when your corporate capital is on the line. It offers no real system, no repeatable process for navigating the unknown.
Many firms attempt to mitigate this risk by simply exporting what they know, assuming a business model successful in Manchester will work in Manila. This is often the first, and most critical, mistake. The real challenge isn’t just adapting to new customs; it’s a fundamental issue of structural integrity. Without the right legal entity, compliance framework, and financial instruments, even the best product is destined to fail, bogged down by unforeseen fines, trapped profits, or a devalued balance sheet.
But what if the entire approach to risk was flawed? The key isn’t to fear volatility, but to engineer control over it. This article abandons the platitudes and instead offers a consultant’s framework for building a resilient international expansion strategy. We will dissect the common failure points for UK businesses and provide concrete, structural solutions—from choosing the right corporate entity to protect your IP, to navigating tax laws for profit repatriation, and finally, to deploying the financial instruments that truly hedge against currency risk. This is your guide to turning fear into a calculated, strategic advantage.
This article provides a structured approach to de-risking your expansion. The following sections break down the critical legal, compliance, and financial challenges you will face and offer actionable frameworks to overcome them.
Summary: A Framework for Investing in Emerging Markets
- Why Do Traditional UK Business Models Fail Miserably in Developing Economies?
- Joint Ventures vs Wholly Owned Subsidiaries: Which Secures Your Intellectual Property Abroad?
- The Compliance Due Diligence Error That Triggers Massive International Fines
- Navigating Complex Local Tax Laws to Repatriate Emerging Market Profits Legally
- When Should a UK Mid-Sized Firm Officially Open Its First Overseas Office?
- Why Do Basic Forward Contracts Often Fail to Fully Protect Mid-Sized Importers?
- Automating VAT Calculations Across Complex Cross-Border European Transactions
- Which Financial Instruments Effectively Hedge UK Businesses Against Currency Risks?
Why Do Traditional UK Business Models Fail Miserably in Developing Economies?
The primary reason UK business models collapse in emerging markets is a flawed assumption: that a successful domestic strategy is a portable asset. It is not. The UK operates within a high-trust, heavily regulated, and stable economic environment. Attempting a « lift and shift » of this model into a low-trust, fluidly regulated, and volatile market is like trying to run a Formula 1 car on a jungle track. It’s built for the wrong conditions. At home, recent UK business statistics reveal that more than 60% of new UK businesses fail within three years; transplanting these already fragile models into a hostile environment significantly worsens those odds.
The failure isn’t just about misreading consumer behaviour. It’s structural. A key, often-overlooked factor is share dilution. As companies in emerging markets frequently issue new shares to fund growth, they consistently dilute the value held by existing shareholders. This means your initial investment can lose significant value even if the local business appears to be growing. Instead of exporting your entire corporate structure, the smarter approach is value chain unbundling: keeping high-value, core functions like R&D and IP ownership securely in the UK, while localising only the necessary customer-facing elements like sales, marketing, and last-mile distribution.
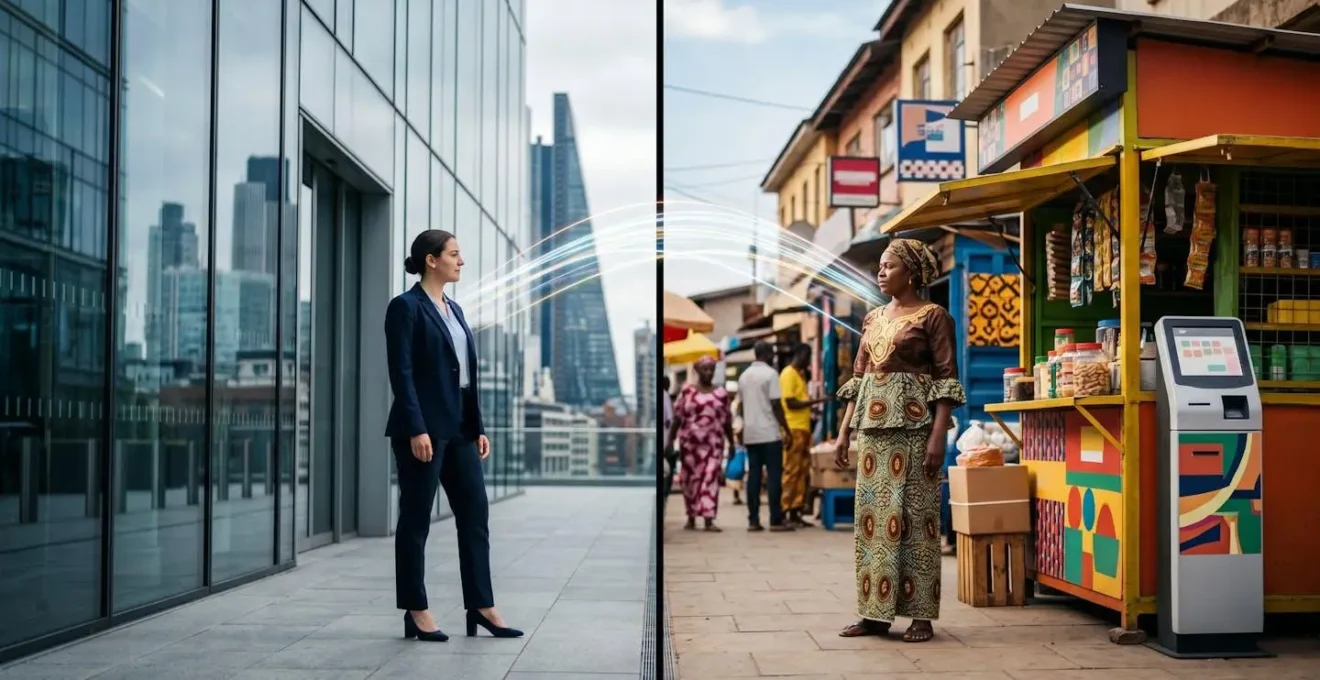
This hybrid model, visualized above, allows a company to maintain control over its most valuable assets while gaining the flexibility needed to adapt on the ground. It minimises the capital at risk and ring-fences your core intellectual property from local operational and legal threats. It is the first step in engineering control over your international expansion, treating the business model not as a monolith, but as a modular system to be strategically deployed.
Joint Ventures vs Wholly Owned Subsidiaries: Which Secures Your Intellectual Property Abroad?
Once you’ve decided to establish a local presence, the choice of legal structure is your single most important decision for protecting intellectual property (IP). The two primary paths, a Joint Venture (JV) with a local partner or a Wholly Owned Subsidiary (WOS), present a classic trade-off between market access and control. A JV offers immediate local knowledge, distribution networks, and political connections, but it forces you to share control and, critically, expose your IP to a third party. A WOS, by contrast, offers maximum control and IP security, but at the cost of a slower, more expensive market entry without local expertise.
For a UK business whose competitive advantage lies in its technology, brand, or proprietary processes, the risk of IP theft in a JV is often too great. The global intellectual property services market is expanding rapidly, projected to become a USD 6.38 billion market by 2030, a clear indicator of how vital—and vulnerable—IP has become. While a WOS is the safest default, if a JV is unavoidable due to local laws or strategic necessity, you must engineer control through an ironclad legal agreement. This goes far beyond a standard partnership contract; it requires building a « compliance firewall » around your IP.
This means embedding non-negotiable clauses that act as automatic triggers to protect your assets. A WOS gives you control by ownership; a well-structured JV agreement must give you control by contract. This involves defining precise, automatic consequences for any breach, ensuring you can reclaim control or exit the partnership without catastrophic loss.
Action Plan: Non-Negotiable Clauses for IP Protection in a Joint Venture
- Points of contact: Mandate arbitration in neutral venues (e.g., Singapore International Arbitration Centre, London Court of International Arbitration) for all IP-related disputes to avoid biased local courts.
- Collecte: Define explicit buyout terms that are triggered automatically by specific IP breaches, allowing you to force the sale of your partner’s stake at a pre-agreed (and disadvantageous) valuation.
- Cohérence: Secure « step-in rights » that allow the UK parent company to take direct operational control of the JV if the IP is deemed to be under threat.
- Mémorabilité/émotion: Structure the venture so that the IP itself is held in a separate holding company located in a jurisdiction with strong investment treaties (e.g., Singapore, Netherlands), and merely licensed to the JV.
- Plan d’intégration: Implement a « black box » system for core technology, where essential software or source code is hosted on cloud servers controlled from the UK, preventing any local access to the core IP.
The Compliance Due Diligence Error That Triggers Massive International Fines
The most terrifying risk for a UK director is not market failure, but a compliance failure that results in crippling fines under the UK Bribery Act or the US Foreign Corrupt Practices Act (FCPA). The critical error most firms make is conducting superficial due diligence. They verify their direct partner’s legitimacy but fail to investigate the entire network of « agents, intermediaries, and associated persons. » This is a fatal mistake, as your company is liable for their actions. Recent enforcement actions, such as the $122 million settlement paid by McKinsey for its role in a South African bribery scheme, demonstrate that regulators show no mercy for ignorance.
The only defence is a forensic-level of due diligence focused on identifying the Ultimate Beneficial Owner (UBO) of every entity in your supply and distribution chain. This means peeling back layers of shell corporations to find the actual individuals who stand to profit. This is non-negotiable because politically exposed persons (PEPs) often hide their interests behind complex corporate structures. A seemingly innocent local logistics partner could be secretly owned by a government minister’s relative, creating a massive bribery risk.
As the visual above suggests, this process is complex and requires specialist help. It is an upfront cost that deters many, but it is insignificant compared to the potential fines and reputational damage. As one compliance expert noted, the legal landscape is unforgiving. As the Mitratech Compliance Report states in its analysis on global anti-bribery trends:
Companies can be held directly responsible for corruption offenses, not just individuals, with fines based on global turnover ensuring penalties are severe and proportionate
– Mitratech Compliance Report, Anti-Bribery Compliance in 2025: Key Global Updates
This means a small compliance slip-up in a foreign market could result in a fine calculated on your entire global revenue, a truly existential threat for a mid-sized UK firm.
Navigating Complex Local Tax Laws to Repatriate Emerging Market Profits Legally
Generating profit in a high-growth market is only half the battle; the other half is getting that money back to the UK legally and tax-efficiently. This is where many businesses get trapped. Emerging market governments are often aggressive in preventing « profit stripping » and impose high withholding taxes on dividends, royalties, and fees paid to foreign parent companies. A naive approach can see 30% or more of your hard-earned profits evaporate before they ever leave the country.
The solution lies in a sophisticated transfer pricing strategy. This involves structuring legitimate, « arm’s length » transactions between your local subsidiary and the UK parent company to move value across borders. For example, instead of only relying on dividends (which often face the highest taxes), you can charge the subsidiary for services rendered from the UK. These can include management fees for executive oversight, IT support, marketing strategy, or royalties for the use of your brand and technology. Each of these methods has different tax implications and compliance requirements.
The key is to ensure all charges are commercially justifiable and thoroughly documented, as tax authorities will scrutinise them. An analysis of OECD guidelines on capital market development highlights the various mechanisms available.
| Repatriation Method | Tax Efficiency | OECD Compliance | Implementation Complexity |
|---|---|---|---|
| Management Fees | 5-15% withholding | High if documented | Moderate |
| IP Royalties | 10-20% withholding | High with arm’s length pricing | Complex |
| Treaty Shopping via Holding Company | 5-10% withholding | Medium (substance required) | Very Complex |
| In-kind Payments | Variable | Case-specific | Moderate |
As the table demonstrates, leveraging a holding company in a jurisdiction with a favorable double-taxation treaty can be highly efficient, but it also adds significant complexity and requires genuine « substance » (offices, employees) to be considered legitimate by tax authorities. This is a prime example of structural arbitrage: using legal and financial structures to navigate disparate regulatory systems for a more efficient outcome. There is no one-size-fits-all solution; the optimal strategy is a blend of these methods, tailored to the specific laws of the target country and your company’s operational reality.
When Should a UK Mid-Sized Firm Officially Open Its First Overseas Office?
The transition from simply exporting goods to establishing a physical office is a major commitment of capital and management focus. Making this move too early can burn cash with little return, while moving too late means ceding ground to more aggressive competitors. A data-driven framework is needed to remove emotion and guesswork from this critical decision. Instead of relying on a « gut feeling, » you should use a staged escalation model based on clear performance metrics and revenue thresholds.
This Market Entry Escalation Framework acts as a series of control triggers. You begin with the lowest-cost, lowest-risk option and only « graduate » to the next stage when specific, pre-defined targets are met. This ensures that your investment level is always justified by proven market traction. The final and most crucial trigger, however, is not a number. It’s people. Do not commit to a full subsidiary until you have identified a trusted, competent Country Manager on the ground. The best strategy in the world will fail with poor local leadership.
Here is a practical escalation framework to guide your decision-making:
- Stage 1 (Exporter): Test the market with minimal investment. Use cross-border e-commerce or a non-exclusive distributor to gauge initial demand. Key metrics to monitor are sales velocity, customer acquisition cost, and inbound enquiries.
- Stage 2 (Local Distributor): When you can project a path to capturing 10-15% of your addressable market segment, partner with an exclusive, dedicated local distributor to scale your presence.
- Stage 3 (Representative Office): Once annual revenue from the market consistently exceeds a threshold like £4-5 million, establish a small representative office. This is not a full legal entity for sales but a base for marketing and partner support, signalling a stronger commitment.
- Stage 4 (Full Subsidiary): Commit to a full Wholly Owned Subsidiary only when you have achieved a sustained growth rate of over 25% for two consecutive years and—most importantly—have the right local leader in place.
This disciplined, phased approach prevents premature capital allocation and aligns your risk exposure with validated market success, providing a structured answer to the « when » question.
Why Do Basic Forward Contracts Often Fail to Fully Protect Mid-Sized Importers?
When UK businesses first venture into emerging markets, their initial tool for managing currency risk is almost always a basic forward contract. It seems simple and effective: lock in an exchange rate for a future transaction, eliminating uncertainty. However, this simplicity is also its greatest weakness. Forward contracts are rigid instruments that fail to protect against several common, and costly, scenarios, giving importers a false sense of security.
First, a forward contract is an obligation, not an option. If the market moves in your favour (i.e., the Pound strengthens against the local currency), you are still locked into the less favourable, pre-agreed rate. You cannot benefit from the upside. This « opportunity cost » can be substantial in volatile markets. Second, they offer no protection against counterparty risk. The contract guarantees a rate, but it doesn’t guarantee your supplier will actually deliver the goods. If the deal falls through, you are still legally obligated to complete the currency exchange, leaving you with a pile of foreign currency you may not need and have to sell back at a potential loss.
Finally, their rigidity makes them unsuitable for businesses with uncertain cash flows. If your payment date shifts—a common occurrence in emerging markets due to logistical delays—your forward contract’s settlement date won’t automatically adjust. This mismatch can force you into complex and costly contract adjustments or a spot market transaction at an unfavourable rate. While forwards are better than nothing, they are a blunt instrument in a world that requires surgical precision. They are part of a hedging strategy, but they are not a complete strategy in themselves.
Key takeaways
- Structural Mismatch: Do not export your UK business model; unbundle your value chain to protect core IP and assets while localising customer-facing operations.
- Engineered Control: Use legal structures (WOS vs. JV), ironclad contracts with trigger clauses, and forensic UBO due diligence to build a « compliance firewall » and manage risk proactively.
- Financial Sophistication: Move beyond basic forward contracts. Use a mix of transfer pricing strategies for profit repatriation and advanced hedging instruments like options and NDFs to truly manage currency volatility.
Automating VAT Calculations Across Complex Cross-Border European Transactions
While your primary focus may be on emerging markets in Asia or Latin America, understanding how to manage tax complexity in a familiar region like Europe provides a powerful template. The EU’s Value Added Tax (VAT) system, with its different rates, reverse-charge mechanisms, and intricate place-of-supply rules, is a perfect microcosm of the tax challenges you will face globally. The key lesson from navigating Europe is that manual management is a recipe for error, and automation is the only scalable solution.
For a UK business selling goods or services across multiple EU countries, calculating the correct VAT for each transaction is a monumental task. You must consider the buyer’s location, their VAT registration status, and the nature of the product (goods vs. services, digital vs. physical). An error can lead to an incorrect invoice, a failed VAT return, and potential penalties from multiple tax authorities. This is precisely the kind of operational drag that erodes profitability from international sales.
Modern ERP systems and specialised tax software can automate this entire process. By integrating with your invoicing and accounting platforms, these tools can:
- Validate a customer’s VAT number in real-time via the VIES database.
- Automatically apply the correct VAT rate based on the customer’s country and the product type.
- Correctly handle complex situations like the reverse-charge mechanism for B2B services.
- Generate the detailed reports needed for accurate VAT filings in each jurisdiction.
This principle of automating tax compliance is directly transferable to emerging markets. While the specific tax might be a Goods and Services Tax (GST) or a local sales tax, the challenge remains the same: managing a high volume of transactions with complex, jurisdiction-specific rules. Investing in a system that can handle this complexity from day one is not an overhead; it’s a critical piece of risk engineering that protects your margins and frees up your team to focus on growth.
Which Financial Instruments Effectively Hedge UK Businesses Against Currency Risks?
Having established that basic forward contracts are insufficient, the savvy UK business owner must turn to a more sophisticated toolkit for managing currency risk in volatile emerging markets. Effective hedging is not about eliminating volatility but about controlling its impact on your profitability. This requires moving from rigid obligations to flexible instruments that allow you to protect against downside risk while retaining the potential for upside gain.
The first upgrade is the currency option. An option gives you the right, but not the obligation, to buy or sell a currency at a specified rate on a future date. You pay a premium for this flexibility. If the market moves against you, you exercise the option to lock in your worst-case rate. If the market moves in your favour, you let the option expire and transact at the more advantageous spot rate. This is the financial equivalent of having comprehensive insurance; you cap your potential loss for a known, fixed cost.
For markets with non-convertible or highly restricted currencies—a common feature in some emerging economies—the essential tool is the Non-Deliverable Forward (NDF). An NDF is a cash-settled contract. No physical currency is exchanged. Instead, you and a financial institution agree on a forward rate. On the settlement date, you compare this agreed rate to the official spot rate. The difference is settled in a major currency like US Dollars or Pounds Sterling. This allows you to hedge your exposure to a local currency’s fluctuations without ever needing to transact in that currency, bypassing capital controls and convertibility issues entirely.
By moving beyond basic instruments and embracing a more sophisticated, multi-layered approach, you can transform currency risk from an uncontrollable threat into a managed business expense. To put these strategies into practice, the next logical step is to consult with a financial specialist to model the specific risks of your target market and build a tailored hedging portfolio.